• The move to the new server is done. There are some software and database maintenance updates in process. This has us passing the hat around to help out. We appreciate any donations. Seriously, even a dollar helps. The payment page may be found here - https://www.audiokarma.org/support.html

AK Retiree Club

Does anyone else get their Social Security checks deposited earlier than the specified Wednesday? Mine got credited at my credit union on Friday again for the second time in two months.

It’s nice getting it early, but what I can find online, it appears to be my CU crediting me early on a guaranteed deposit. Anyone else enjoying this nice spiff?
They do it with my military retirement check....usually 2 days ahead.
 
Does anyone else get their Social Security checks deposited earlier than the specified Wednesday? Mine got credited at my credit union on Friday again for the second time in two months.

It’s nice getting it early, but what I can find online, it appears to be my CU crediting me early on a guaranteed deposit. Anyone else enjoying this nice spiff?
I checked a few months and they were all on Wednesday.
 
Newbie to the group.

Will be 65 in 2 years so I'm waiting to retire then to save money on health insurance.

Trying to plan now by getting healthier and looking for our retirement house. Neither one is easy, but definitely necessary!

Looking to get into a modest ranch home on some acreage with an attached garage.

For those in their "forever home", what attributes do you really appreciate or miss that I can learn from.

Thanks, and I envy all of you retiree's!

PS: my corp job's not that difficult, and my boss stays off my arse, so I can hang in for 2 more seasons.
We looked at our forever home with 2 criteria; one how did we actually live in our current home and secondly how did we expect to be living 20-30 years into retirement.

When we looked at the first criteria we realized we never made use of certain rooms like our formal living room or dining room so they would not be rooms we needed in retirement. We still wanted 3 bedrooms so we could use one bedroom as a guest bedroom and the other as my music room. A covered patio that can be converted into another room also gives some flexibility should the need for more space

Looking at the second criteria we opted for a floor plan with no stairs so all the house will be accessible as we age. The doors are wide enough to easily allow a wheelchair/walker if one becomes needed. The master bathroom has a walk in shower with a built in seat should that be needed in the future. Both bathrooms have elevated toilets that make for easier use now and in the future if a wheelchair/walker are in use. Light switches are low on the walls and there are plenty of outlets in each room.

While we enjoyed a large backyard and several gardens at our previous house we opted for a smaller yard and garden boxes for the new house. All lawn maintenance is included in the HOA fee. We have access to two nearby clubhouses with pools and exercise facilities that we use to stay fit.

There are only really two draw backs to our housing choice. My music room is now only 12x12 compared to the 16x20 with vaulted ceilings that was my previous music room. Eventual I figured out how to make it work and it is now a great space to listen to music for years to come. The second drawback is that mail is not delivered directly to the house but rather a central mail area just down the street. The amount of important mail we receive has dropped dramatically so visits to get mail are only once or twice a week in any case.

Last thing I will mention regarding our retirement housing choice is that we opted for a practical home rather than a statement house. While we certainly could have bought a larger house with features that reflected that I earned a good living and made good financial decisions, we opted for a home we will be able to live in if our health declines and that won’t be a burden for our children to dispose of when the time comes.

Good luck on your retirement journey!
 
Does anyone else get their Social Security checks deposited earlier than the specified Wednesday? Mine got credited at my credit union on Friday again for the second time in two months.

It’s nice getting it early, but what I can find online, it appears to be my CU crediting me early on a guaranteed deposit. Anyone else enjoying this nice spiff?
Ours get deposited a full day before the scheduled date. We also co-ordinated our Social Security payments with our monthly portfolio withdrawal so that roughly we are getting paid every two weeks just like it was when I was working.
 
I do the same here with my savings withdrawals.

I just found it odd that it has changed after almost 4 years of Wednesday checks. My wife still gets hers in her bank on the 2nd Wednesday, so it’s definitely related to my credit union and something new.
 
Mine has always been scheduled to be in the bank on the 3rd of every month but, it depends if there's a holiday on the 3rd or that it falls on a Sunday.
If so I get it on the 2nd and this happens about 6 times out of the year I think. But, one thing I can say for sure is it's never late and there's a lot
of things nowadays that I can say that about, in fact I can't think of one other thing that hasn't been late more then once.

As far as Retiring being oh so fun, I don't see it that way at all, I'd much rather be working. Of course I was forced into retirement when I was 49 or 50 when my back suddenly went out because of collapsing discs. Sadly I wasn't as prepared for retirement as I should have been but, I made up for what SS didn't cover by being a pipe-maker (hand made smoking pipes (tobacco)) for ten years and did very well until I found I could no longer do that either. Still try to make a little here and there when I can and at 72 now I find myself spending the little savings I have on my hobbies and try to enjoy my life, so far it's working. ;)
 
I've never thought about when or on what day. I make withdrawals from my retirement fund, which is what really makes something to look at; as it is done monthly and I know it is always there.
 
My wife and I are both retired federal employees receiving both a pension and SS. Neither my pension or SS are credited early by my bank. I have never heard my wife mention that her credit union credits her SS early but they do often credit her pension payment 2-3 days early.
 
I'm a county employee and my org has an agreement with the CU I use.

My check is generally deposited 2 days prior to the day I would get a paper check.

However, in the case of holidays that fall a few days before a pay date, it an be as early a 4 days.


On my calendar today is to call the retirement counselor at my state's pension administrator.

To see if I need to retire today, or wait out the fiscal year.
 
C'mon DOW, match yer brother indices S&P and NASDAQ by COB this week.
Markets are being moved by algorithms seeing positive words more than positive results. We moved to a 45/55 stock/bond mix with more of a tilt towards International stock funds over Domestic funds before the Iran situation. Not trying to time the market just buying some peace of mind from the chaotic headlines that seem to come every other day that cause such wild swings.
 
Markets are being moved by algorithms seeing positive words more than positive results. We moved to a 45/55 stock/bond mix with more of a tilt towards International stock funds over Domestic funds before the Iran situation. Not trying to time the market just buying some peace of mind from the chaotic headlines that seem to come every other day that cause such wild swings.
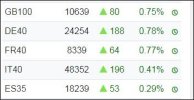
If your international positions lean more toward European bourses, then you'd have loved today's trading:

EU.JPG
As of 2:05 PM PARIS TIME
 
Well....I was kind of planning to "retire" from my job after 30.8 years at the end of Florida government fiscal 25/26 (June 30).

However, with the past several years of around 10-15% inflation, it has become clear that I can seriously benefit from working one more year while taking the Deferred Retirement Option Program). "DROP" allows you to continue working, but stops the collection of contributions to your state retirement account, both from your paycheck and from the state. This effectively yields a small salary increase, in my case, about 70 bucks every 15/16 day pay period. Additionally, you start receiving retirement payments, which for me will be equal to about 48% of my salary. Those funds are kept in an account that yields 4% interest. Also, after a year, the COLA is applied. If I actually stop working at that time, my next years retirement will be at the "year 2" COLA rate.

I almost can't afford not to do this.

I'm kind of trapped as I was just past the 15 year mark when the state revised their retirement COLA calculations, and basically stopped giving a COLA to new hires.
It had been 3%. All those currently in the system got a calculation based on years of service prior to the reorg. As it stands, my COLA calculation is 1.6%.
The trapped part comes in because, as I work longer past my "30 year" mark, those additional years count towards the "zero COLA" side of the calculation, and reduce the percentage. By my calculations, I should still have a 1.5% COLA when my DROP paperwork goes through. It's not going to keep up with inflation, but it's better than a fixed income.

 
However, with the past several years of around 10-15% inflation,
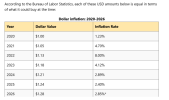
Well, there's inflation, but it hasn't been annually near 10% for years. It was and it is a concern, but 10%+ annually is overstating it. It is up 28% since 2020 overall though.

1776360162790.png
 
Last edited:
If your international positions lean more toward European bourses, then you'd have loved today's trading:

View attachment 3743357
As of 2:05 PM PARIS TIME
Well they are fairly diverse across the World but more importantly they are not as Tech heavy as my Domestic funds. Currently my International is up 5% over my Domestic funds and they have outperformed my Domestic funds by 6-8% for the past 3 years. Just trying to get by that first 5 years of Sequence of Return risk without any major setbacks. This is year 4 so fingers crossed!
 
Well they are fairly diverse across the World but more importantly they are not as Tech heavy as my Domestic funds. Currently my International is up 5% over my Domestic funds and they have outperformed my Domestic funds by 6-8% for the past 3 years. Just trying to get by that first 5 years of Sequence of Return risk without any major setbacks. This is year 4 so fingers crossed!
Seconding that!
 
Back
Top Bottom